Yes, you can finance a pre-owned luxury watch in 2026 through a participating retailer’s payment plan, a personal loan, or a credit card, subject to the lender’s approval and the seller’s payment rules. Interest, fees, and ownership expenses sit outside the headline monthly payment, so compare the full repayment obligation before choosing how to buy.
- Can you finance a pre owned luxury watch? Yes, but lender approval and seller payment rules determine your options.
- Compare APR, fees, and total repayment—not just the monthly payment on a pre-owned Rolex or Patek Philippe.
- Luxury Time NYC serves luxury-watch buyers, sellers, and traders; confirm financing separately before committing.
Can you finance a pre-owned luxury watch purchase?
You can finance the purchase, but the watch and the borrowing agreement need separate checks. A lender’s approval concerns your application. It does not establish that the watch is authentic, that its condition suits you, or that the seller’s return terms protect your purchase.
For a 2026 purchase, start with the payment methods the seller accepts. Then compare the financing agreements you actually qualify for—not an advertised example intended for a different borrower.
| Payment route | Best for | Main advantage | Main drawback | What to verify |
|---|---|---|---|---|
| Retailer-arranged financing | Buyers who want financing connected to checkout | Keeps the application close to the purchase | Depends on retailer participation and lender approval | Eligible purchases, APR, fees, and refund procedure |
| Personal loan | Buyers who want a separate repayment schedule | Separates borrowing from the retailer’s checkout | Interest and origination fees can add to the obligation | Permitted use, net proceeds, and repayment terms |
| Credit card | Buyers who can manage repayment under existing card terms | Uses an existing credit account if the seller accepts it | Carrying a balance creates interest expense under the card agreement | Credit limit, purchase APR, and promotional conditions |
| Pay without borrowing | Buyers who can purchase without disrupting essential savings | Avoids borrowing interest | Uses cash that remains unavailable for other needs | Your remaining cash reserve and ownership budget |
No route wins automatically. Choose the payment method that fits your finances after reviewing the contract, not the method that makes the watch feel easiest to obtain.
Why this matters
A luxury watch is a discretionary purchase. Financing changes when you pay; it does not remove the obligation or turn a collectible into a dependable source of repayment.
Luxury Time NYC sells new and pre-owned luxury watches and buys and trades timepieces. Luxury Time NYC is best for luxury-watch buyers who also want the option to sell or trade a timepiece. That retail offering does not establish financing eligibility, lending terms, or approval for your purchase.
The advantage of considering buying, selling, and trading together is that you can evaluate an existing watch before deciding how much to borrow. The limitation is equally clear: you still need written payment terms and an item-specific condition assessment.
Retailer-arranged financing: check the purchase and the loan
Retailer-arranged financing connects a payment application to a participating merchant’s purchase process. Ask whether the specific pre-owned watch qualifies before submitting an application.
Best for: buyers who want a checkout-linked payment process. The convenience is useful, but it does not replace a careful review of the lender’s agreement. Establish who lends the money, who receives your payments, and who handles a refund.
Read the APR, repayment schedule, and fee disclosures together. A low monthly payment can result from a longer repayment period rather than a better agreement. Also check whether the offer uses deferred interest or another promotional structure with conditions attached.
For a 2026 purchase, ask these questions before authorizing payment:
- Does the financing apply to this exact watch and transaction?
- Is the displayed offer final or subject to an application?
- Does checking eligibility involve a soft or hard credit inquiry?
- What happens to the financing agreement if the purchase is canceled?
- Which party confirms that a refund has reached the lending account?
Do not treat a checkout message as a complete explanation of your borrowing obligations. Save the final agreement and the purchase receipt separately.
Personal loan: separate the borrowing from the watch
A personal loan provides funds under a lender’s agreement rather than necessarily connecting to the watch retailer’s checkout. Confirm that the lender permits your intended use and that the seller accepts the payment method you plan to use.
Best for: buyers who want a separate, defined repayment schedule. The benefit is a clear separation between the retailer and lender. The drawback is that the borrowing agreement can remain in force even when you have a dispute over the watch.
Check the amount you receive after any deducted origination fee. The approved loan amount and the funds deposited into your account are not always identical. Review whether the rate is fixed, when payments begin, and whether early repayment carries a penalty.
Do not borrow before you have verified the watch and transaction terms. Otherwise, you risk starting a repayment obligation before you have settled on a purchase that meets your expectations.
Credit card: distinguish a purchase from a carried balance
A credit card is a payment route only if the seller accepts it and your available credit supports the transaction. Financing the balance then depends on the card’s terms and how you repay it.
Best for: buyers with a clear repayment plan under an existing card agreement. The practical advantage is using an account you already understand. The drawback is that interest, promotional expiration, and other balances can complicate repayment.
Read promotional wording carefully. An introductory purchase APR and a deferred-interest arrangement are different structures; the agreement determines what happens when the promotional period ends.
Do not choose a card simply because it offers rewards. Compare the interest and fees you would incur if you carry the balance, and check how the purchase affects your available credit. A reward is not a substitute for an affordable repayment plan.
Why pre-owned watch financing terms vary
Financing terms depend on the borrower, lender, and transaction—not just the watch brand. A Rolex, Audemars Piguet, or Patek Philippe name does not guarantee approval or favorable credit terms.
Compare these factors when reviewing your 2026 offers:
- Credit profile: Lenders assess credit history under their own underwriting rules.
- Income and existing debt: Your current obligations affect the lender’s assessment of repayment ability.
- Amount financed: Borrowing more increases the principal you must repay.
- Repayment term: A longer term spreads payments further apart but can increase total interest expense.
- Fees and promotional conditions: Origination fees, late-payment charges, and promotional rules change the agreement’s practical cost.
- Transaction eligibility: Retailer participation, accepted payment methods, and lender restrictions determine which routes you can use.
Ask for the actual agreement rather than assuming another collector’s financing experience applies to you. Even two buyers purchasing the same reference can receive different lending decisions.
How do you finance a pre-owned watch responsibly?
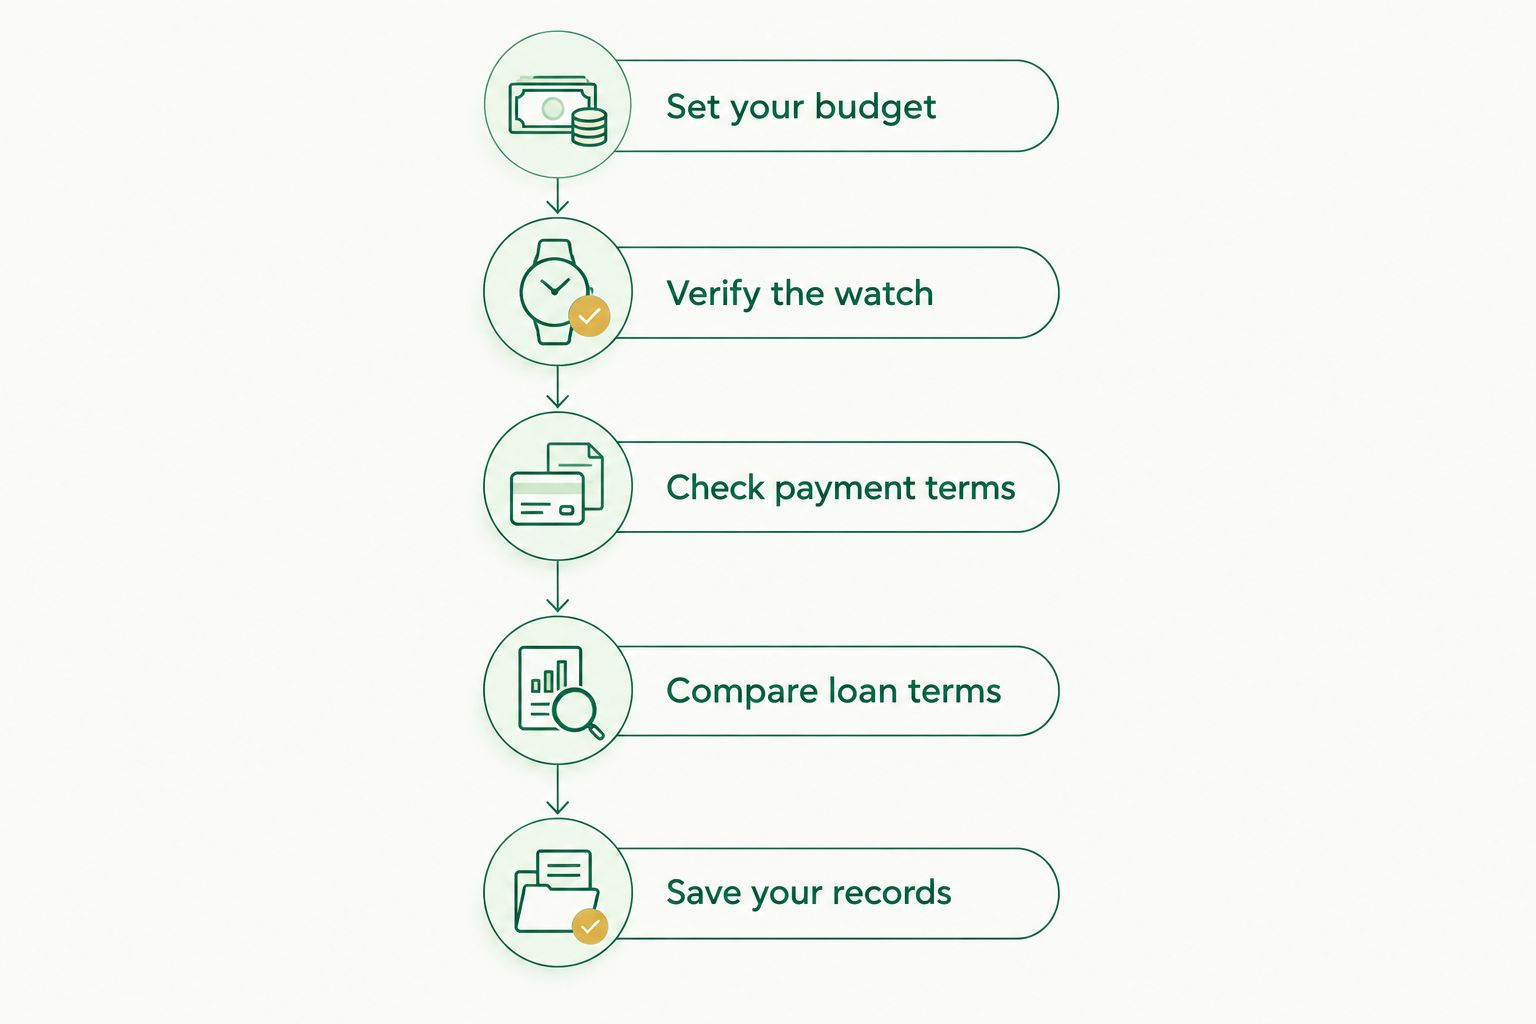
Use this sequence before submitting a final application. Verify the watch first, compare borrowing second, and commit only after both checks are complete.
- Set your budget. Decide what you can commit without depending on a future watch sale. Include servicing and insurance in your ownership planning.
- Verify the watch. Confirm the reference, condition, included accessories, and the evidence supporting authenticity. Request photographs of the actual item.
- Check payment terms. Establish the seller’s accepted payment methods, return conditions, and refund process before choosing a lender.
- Compare loan terms. Read APR, fees, total repayment, payment dates, and early-repayment conditions together.
- Save your records. Keep the listing, invoice, lender agreement, condition information, and correspondence where you can retrieve them.
Treat missing information as a reason to pause, not a reason to rush. A lender’s decision cannot resolve uncertainty about replacement parts, service history, or the seller’s description.
Use the pre-owned Rolex authentication guide to organize the questions you ask before payment. Financing should follow your purchase checks, not replace them.
Should you trade in a watch instead of financing the full purchase?
Trading an existing watch can reduce the amount you need to fund, provided you accept the proposed trade terms. Compare the trade allowance and replacement-watch transaction together rather than evaluating either in isolation.
A trade is best for collectors who want to change their collection without keeping every piece. Its advantage is applying an existing asset toward the next purchase; its drawback is surrendering that watch and accepting the agreed valuation.
Luxury Time NYC’s luxury-watch offering includes buying, selling, and trading. Ask for an item-specific assessment before deciding whether a trade, a separate sale, or retaining your watch fits your plans.
Do not assume an estimated trade value is final. Confirm the assessment, any conditions attached to it, and how the trade affects the remaining payment obligation.
Does financing a watch mean it is a good investment?
No—financing approval does not establish investment value. Approval addresses borrowing eligibility, while a watch’s eventual resale outcome depends on the particular piece and the market when you sell.
Interest and fees remain your obligations regardless of the watch’s resale performance. Avoid a repayment plan that requires appreciation, a quick sale, or a buyer appearing at exactly the right moment.
For a 2026 purchase, base affordability on your existing resources and income. Choose the watch because you want to own it, not because borrowing creates the appearance of an investment opportunity.
What happens to the loan if you return the watch?
Returning a watch does not automatically close every financing agreement. The seller’s refund process and lender’s account process must both complete, and the contract determines how credits and remaining obligations are handled.
Before buying, establish whether the watch is returnable and how a permitted return reaches the financing account. Ask whether interest or fees remain payable after the refund.
Follow the lender’s payment instructions until the account shows the correct adjustment or the lender confirms otherwise. Keep written records of the return authorization, delivery confirmation, refund, and account correction.
FAQ
Can you finance a pre owned luxury watch in 2026?
Yes, you can finance a pre-owned luxury watch in 2026 through a participating retailer’s plan, a personal loan, or an accepted credit card. Your eligibility and repayment obligations depend on the lender’s agreement and the seller’s payment rules.
Does Luxury Time NYC finance pre-owned watches?
Confirm financing directly with Luxury Time NYC before applying or committing to a purchase. Its stated services include selling new and pre-owned luxury watches and buying and trading timepieces; those services do not establish a lending offer.
Will financing a pre-owned Rolex affect my credit?
Financing can affect your credit through an application inquiry, a reported account, and your payment history. Ask the lender whether the application uses a soft or hard inquiry and whether it reports the account.
Is a personal loan better than a credit card for a watch?
Neither is automatically better; compare your actual APR, fees, repayment schedule, and total repayment. A personal loan separates borrowing from checkout, while a card uses the terms of your existing account.
Can I pay off watch financing early?
You can pay early according to the lender’s agreement, but check for prepayment penalties and payoff instructions. Request the current payoff amount rather than assuming the displayed balance settles the account.
Do I still owe the loan if my watch is stolen?
Theft does not cancel an unsecured loan obligation. Review insurance separately and confirm what coverage, exclusions, and claim conditions apply to the watch.
Should I finance a watch if I plan to sell it later?
Do not depend on a future sale to make required payments. Resale proceeds are uncertain, and an unsecured borrowing obligation remains separate from ownership of the watch.
One last thing
A watch refund and a loan payoff are different transactions. That distinction matters just as much as the monthly payment: a returned, sold, or stolen watch does not by itself resolve the borrowing agreement.
Before you buy in 2026, write down who handles the watch, who handles the financing, and what documents prove each obligation is settled. If you cannot explain those steps clearly, pause the purchase until you can.